THE STRATEGIC HOME BUYER’S GUIDE
Buying your first Tri-Valley home isn’t simply about finding the right property. It’s about knowing whether you’re financially ready, choosing the right community, understanding property and disclosure risk, competing intelligently, and staying in control through inspections and closing.
This guide is designed for first-time buyers in Danville, San Ramon, Pleasanton, Dublin, Alamo, and nearby East Bay communities who want a clear decision process rather than a sales pitch.
My role isn’t to convince you to buy a home. It’s to help you make a decision you can feel confident about.
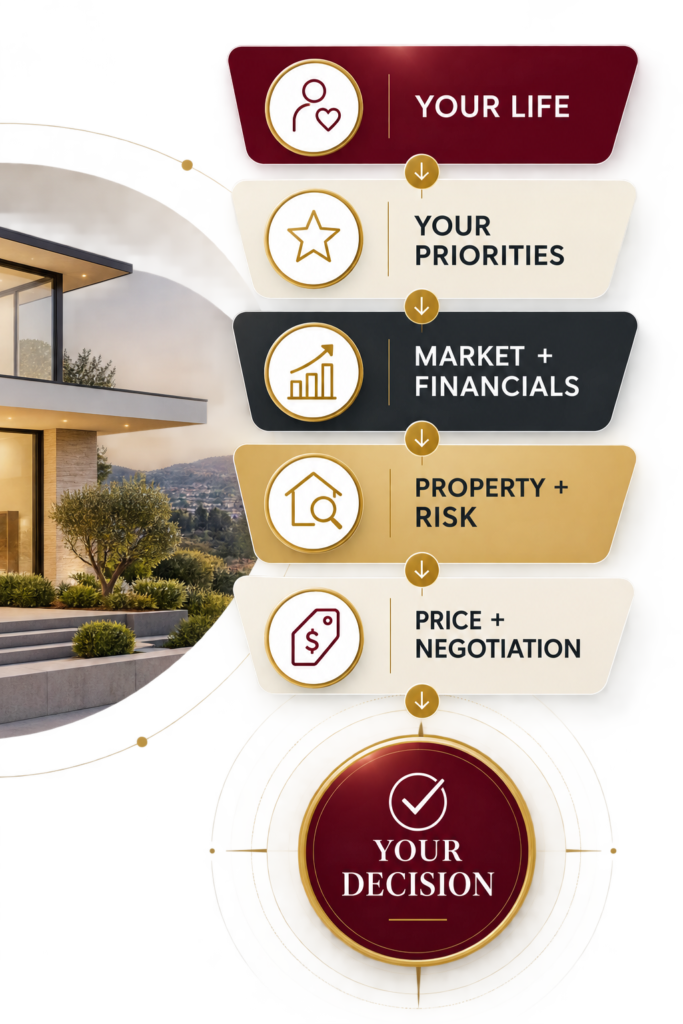
01 · DEFINE THE DECISION
Before we talk about bedrooms, square footage, or price, there’s a more important question:
Family
Career
Commute
Schools
Lifestyle
Location
Space
Community
Timing
Financial Goals
Must Have
Prefer to Have
Flexible On
Won’t Compromise
Search Criteria
Financial Framework
Market Strategy
Decision Framework
Our first job is to understand what “right” means for you.
02 · BUILD THE FINANCIAL FRAMEWORK
The purchase price is only one part of what a home actually costs. In the Tri-Valley, first-time buyers should model the payment using the actual purchase price, down payment, interest rate, property taxes, homeowners insurance, and any HOA or special assessments.
For example, on a $1.25M purchase, 20% down means $250,000 before closing costs and reserves. A 10% down payment reduces the upfront cash but increases the loan amount, and may add mortgage insurance depending on the loan. California property taxes are generally based on assessed value, with local bonds, Mello-Roos, and other assessments varying by property. HOA dues can also materially change the monthly cost.
I’ll help you compare the complete ownership picture, but your lender, tax professional, insurance professional, and other qualified advisors should confirm financing, tax, insurance, and legal implications for your situation.
03 · UNDERSTAND THE MARKET
A home doesn’t exist in isolation. Inventory, comparable sales, days on market, price changes, and buyer behavior all provide signals. Those signals can differ between Danville, San Ramon, Pleasanton, Dublin, and Alamo, and even from one neighborhood to another.
Before shaping an offer, we’ll review recent sales, current competition, market time, pricing changes, disclosures, and property-specific considerations. You can also use the Buyer Timing tool and local market reports to put today’s conditions in context.
How much choice do buyers have?
What has the market recently validated?
How quickly is demand responding?
How many buyers may be competing?
Where are sellers adjusting?
What are buyers actually responding to?
data + context
One comparable sale doesn’t establish value. One price reduction doesn’t define a trend. One multiple-offer sale doesn’t mean every home will behave the same way.
The advantage comes from understanding how the signals fit together.
My role is to help you separate signal from noise, understand the tradeoffs, and make that decision with the best evidence available.
04 · SEARCH WITH PURPOSE
Search filters are useful, but they only describe a property. The real question is how well that property fits your priorities, your financial framework, and the life you’re trying to build.
In the Tri-Valley, compare more than bedroom count and square footage. Consider commute patterns, school-district boundaries, neighborhood age and character, HOA structure, lot size, wildfire or insurance considerations where relevant, access to parks and downtown areas, and the ownership costs that can differ from one neighborhood to another.
Does this home move you closer to what you're trying to accomplish?
The search gets more effective when every property is evaluated against the decision framework we established before it began.
A showing tells you how a home feels. Careful evaluation helps you understand what you may be taking on—today, over time, and when you eventually sell.
What is working, aging, or nearing replacement?
What has the seller disclosed, and what needs clarification?
What do qualified professionals reveal about the home?
Which issues are routine, material, or still unknown?
What changes are optional, necessary, or value-enhancing?
How well will the property serve your plans over time?
List price is a marketing decision. Market value and offer strategy require a broader view of comparable sales, current competition, property-specific strengths, buyer demand, and your objectives.
We decide where price matters, where terms create leverage, what protections you need, and where flexibility may improve the outcome—before emotion takes over.
A real estate agreement is a connected set of financial, timing, risk, and performance terms. Good negotiation protects what matters most while creating a path the other side can accept.
Once your offer is accepted, the work becomes more coordinated—not less. Each milestone has dependencies, deadlines, and decisions that need to stay aligned.
Confidence doesn't come from removing every unknown. It comes from understanding the decision well enough to choose deliberately.
Does it support what you're trying to accomplish?
Does the complete cost make sense?
Do you understand its condition and risks?
Does the strategy fit the evidence?
Every purchase is different, but these are useful starting points. Your financing, timing, goals, and the specific property will shape the final strategy.
Plan for more than the down payment. Your framework should also account for closing costs, inspections, reserves, moving expenses, and near-term ownership costs. The right amount depends on your loan program and the financial cushion you want to preserve.
Yes. A strong pre-approval clarifies your price range, estimated payment, cash requirements, and potential loan constraints. It also allows you to act decisively when the right property appears.
Value is not established by list price alone. We evaluate relevant comparable sales, current competition, condition, location differences, buyer demand, and the cost of your alternatives before shaping an offer strategy.
The appropriate inspections depend on the property, disclosures, age, construction, and known risks. A general home inspection is often the starting point, with specialists brought in when the evidence calls for deeper evaluation.
Escrow opens and the inspection, financing, appraisal, disclosure review, contingency, and closing timelines begin. Each milestone has deadlines and dependencies that need to stay coordinated.
Walking away may be the right decision when new information materially changes the property risk, financial fit, contractual protection, or alignment with your goals. Confidence includes knowing when not to proceed.
We'll begin with your goals, questions, timing, and concerns—then decide what a smart next step looks like for you.
Start a Buyer Conversation